Pinegrove's $1.5bn fund of funds shows where cautious pension money still enters venture
Strategic Investors Fund XII closed oversubscribed with Florida's state pension board as anchor. Its appeal lies less in manager picking than in the access a full venture platform can sell.
Pinegrove Venture Partners said on Thursday that it had held the final close of Strategic Investors Fund XII at $1.5bn, split between an early-stage strategy and a later-stage one. The firm said the fund was significantly oversubscribed, with demand well above its target, and that the Florida State Board of Administration, which manages the state's public pension assets, had anchored it.
A fund of funds raising $1.5bn would once have been a footnote. In the current market it is a useful piece of evidence. Large institutions have spent the past few years complaining that venture capital returns too little cash too slowly, and many have cut their allocations or concentrated them in a few established firms. Pinegrove's close suggests that some of the most conservative money in America is still prepared to commit fresh capital to the asset class, provided it can do so through an intermediary that promises selection, access and a wider set of tools than a single venture firm can offer.
How the fund is built
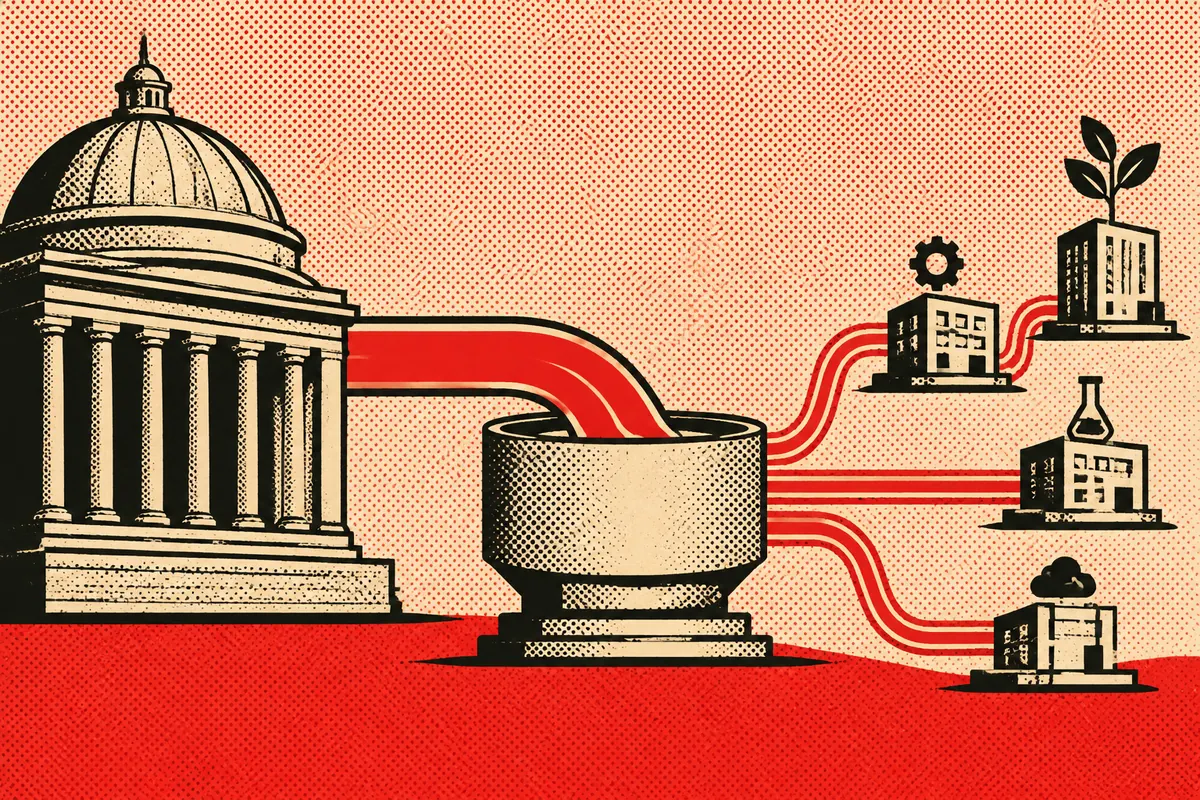
The Strategic Investors Fund programme has run for more than 26 years, according to Pinegrove, and its method is simple to describe. Institutions commit to the fund, and the fund commits to a concentrated group of venture managers, established and emerging, who in turn back startups. SIF XII has two sleeves. SIF XII-Early invests with early-stage managers. SIF XII-Scale invests with expansion-stage managers and makes selective co-investments alongside leading general partners. Pinegrove has not disclosed how the $1.5bn is divided between the two, nor which managers receive allocations.
The fund will invest across a 3-year vintage, the firm said, in a period it describes as one of accelerating innovation in artificial intelligence, infrastructure, enterprise software, healthcare, life sciences and defence. Pinegrove also said the fund had already provided exposure to leading private technology companies through its managers and co-investment programme, which suggests that part of the capital was already at work before the final close.
Why a pension board wants an intermediary
For a public pension, the case for a fund of funds is mostly about access. The venture firms that have produced the strongest returns tend to keep their funds small and their investor lists closed. A programme with relationships going back more than 2 decades can secure allocations that a newcomer, however large, would struggle to obtain. John Bradley, head of private equity at the Florida State Board of Administration, described Pinegrove as one of the board's most important and successful partnerships and its route into the innovation economy.
The obvious cost is an extra layer of fees on top of those charged by the underlying venture managers. Pinegrove's answer is that it offers more than manager selection. The firm says its relationships give it an information advantage and let it put together co-investments, bespoke portfolios and what it calls strategic capital opportunities, tailored to each investor's pacing and risk limits. Co-investments, which usually carry lighter fees, are the part of the offer most likely to reduce the blended cost for limited partners.
A platform, not a single fund
The more interesting point is what sits around SIF XII. Pinegrove now describes itself as an integrated platform with more than $15bn of assets under management across 3 businesses: venture fund primaries and co-investments, venture debt and private credit, and venture and growth secondaries. It is backed by HRTG Partners and Brookfield Asset Management.
The platform was assembled quickly. In May 2024, SVB Financial Group, the parent of the collapsed Silicon Valley Bank, agreed to sell its investment platform, SVB Capital, to an entity affiliated with Pinegrove, with Brookfield and Sequoia Heritage providing long-term backing, according to the announcement by Pinegrove's lawyers. In January this year Pinegrove Opportunity Partners, the secondaries arm, closed its first fund at $2.2bn, above a $2bn target. That vehicle buys stakes in mid to late-stage private technology companies through company tender offers, continuation vehicles, purchases of fund interests and loans against net asset value.
Put together, these businesses let Pinegrove see the venture market from several angles at once: as a limited partner in many funds, as a lender to startups, and as a buyer of stakes from investors who want to leave early. Anuj Ranjan, who heads private equity at Brookfield, credited managing partner Aaron Gershenberg, Sulu Mamdani, Thorben Hett and the wider team with deepening the firm's position among venture managers and institutional investors. The commercial logic is that information gathered in one business informs decisions in the others.
What it says about the market
Two features of the close stand out. First, the anchor is a state pension board, not a sovereign fund or a family office. That matters because public pensions answer to beneficiaries and boards that watch cash returns closely. Their willingness to commit again, through a diversified vehicle, implies that the liquidity squeeze has not destroyed long-term demand for venture exposure. It has changed its form.
Second, the pairing of primaries with a large secondaries business is becoming the model for intermediaries in this market. Investors who commit to new funds also want a credible buyer when they need to rebalance, and managers who sell secondaries want insight into which funds are performing. A platform that can offer both has an edge in winning mandates.
Our view
SIF XII is a reminder that institutional appetite for venture capital has not vanished; it has become more selective about how it is expressed. A conservative anchor, a long track record and a platform that can lend, co-invest and buy secondaries proved a stronger pitch than a single fund strategy. For limited partners, the advantages are real, but so is the extra layer of fees, and Pinegrove's undisclosed split between early and scale strategies makes it hard to judge how much of the fund is exposed to today's richly priced late-stage AI rounds.
For venture managers, the message is clear: securing an allocation from programmes like this one is increasingly a gateway to pension money. For founders, the effect is indirect but positive, since more committed capital flows to the funds that lead their rounds. What to watch is the pace of distributions from the SIF programme's earlier vintages. If they improve, others will follow Florida's lead; if they do not, the oversubscription will look like a high point.
Sources
- PR Newswire: Pinegrove closes $1.5 billion oversubscribed Strategic Investors Fund XII
- Value Add VC: Pinegrove closes $1.5B fund of funds, oversubscribed
- Paul, Weiss: Pinegrove to acquire investment platform business SVB Capital
- Pulse 2.0: Pinegrove Opportunity Partners raises $2.2 billion for inaugural fund
- Alternatives Watch: Pinegrove Opportunity Partners closes venture secondaries fund
Filed under Venture Capital. Written by Invest Times Editorial under our editorial standards. Commentary and analysis for information only, not investment advice.