The Fed puts a price on bank-issued stablecoins, and it is mostly operational risk
Two Federal Reserve proposals under the GENIUS Act set reserve rules, a graduated capital charge and a licensing path for bank stablecoin subsidiaries. The numbers will shape who can afford to issue.
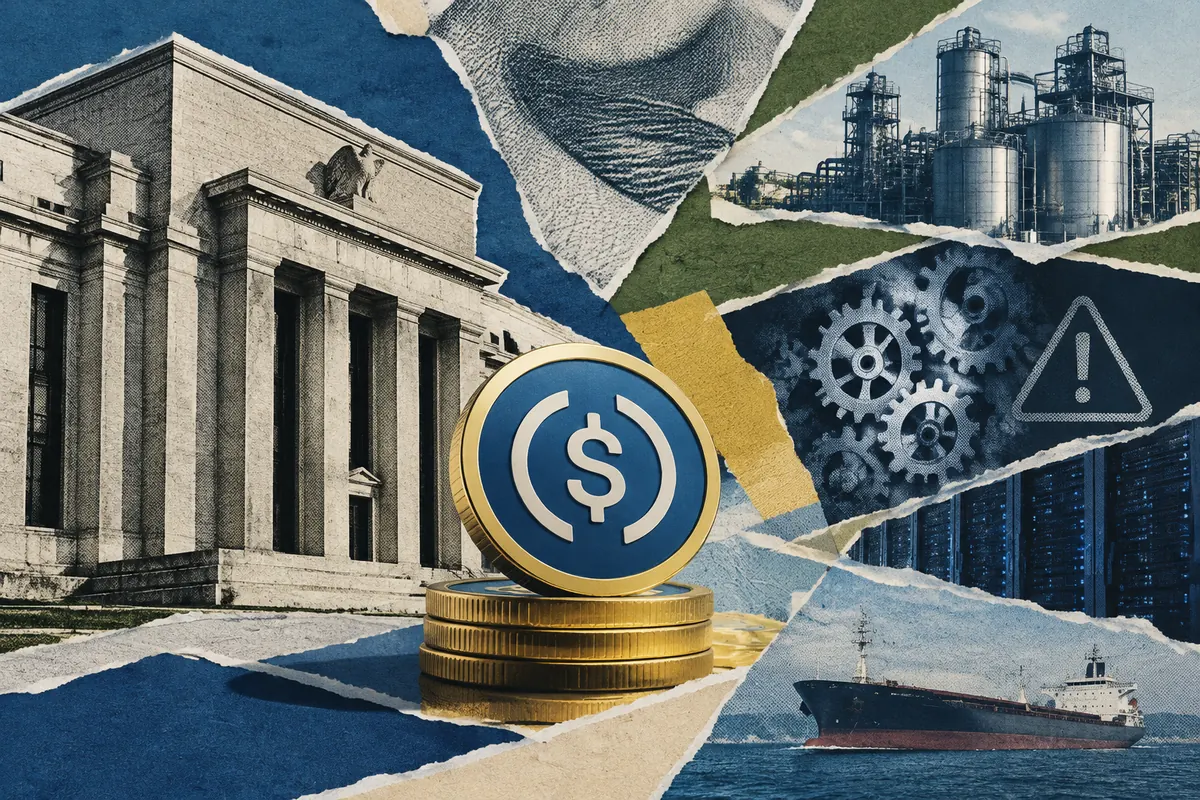
The Federal Reserve has finally said how much capital it wants behind a dollar stablecoin issued from inside the banking system. On Thursday, September 24, the Board of Governors asked for public comment on two proposals that implement its share of the GENIUS Act, the stablecoin law signed in July 2025. The first sets reserve, capital, redemption and risk management rules for the payment stablecoin issuers the Fed supervises, and writes the act's ban on tying for every issuer in the country. The second sets out how a state member bank applies for permission to issue a stablecoin through a subsidiary. Both passed on unanimous votes, according to PYMNTS, and each will be open for comment for 60 days after it appears in the Federal Register.
The package matters beyond the relatively small group of banks the Fed regulates directly. It arrives after the Office of the Comptroller of the Currency, the FDIC, the NCUA and the Treasury have all published their own GENIUS Act proposals, and it completes the outline of what a regulated American stablecoin will cost to run. For fintech companies, crypto firms and the banks that want to compete with them, the economics of the business are now visible on paper for the first time.
What the reserve rules allow
The core requirement is the one the statute already imposed: reserve assets must have a fair value at least equal to the par value of every coin outstanding, at all times. The Fed's staff memo spells out what counts. Eligible reserves are US dollar cash, Federal Reserve Bank balances, demand deposits at insured institutions, Treasuries with 93 days or less to maturity, overnight repurchase and reverse repurchase transactions tied to Treasuries, shares in funds that hold only those assets, and tokenised versions of some of them. Reserves must be segregated from the issuer's other assets.
An issuer that slips below full backing would have to notify the Fed and then liquidate its reserves and redeem its coins, unless it has a credible plan to restore the shortfall and the Board tells it to proceed. Redemption policies must be public, with a redemption period of no more than two business days unless a safe harbour applies, although the Board keeps discretion to extend that period if an issuer's safety or financial stability is at risk.
Diversification is principles based rather than numerical. Issuers would have to manage concentration in uninsured deposits held at one or a few banks, and in reverse repo exposure to a small number of counterparties. That choice leaves room for supervisory judgement, which is precisely what Governor Michael Barr wants the public to test.
The capital charge is where the economics sit
The most consequential numbers are in the capital section. The proposal imposes a 2 percent charge on reserves that are uninsured deposit claims or undercollateralised reverse repos, applied on a look-through basis to fund holdings. Reserves held in Treasury bills or at the Fed carry no credit charge, which pushes issuers firmly towards the safest assets.
The larger charge is for operational risk. It is graduated: 2 percent of the first $20bn of stablecoins outstanding, 1.5 percent of the next $30bn and 1 percent above $50bn. On top of that sits a charge equal to 25 percent of the three-year average of revenue that does not come from reserve assets, such as custody fees. A loss scalar would move the requirement up or down depending on actual operational losses.
By our own arithmetic on the proposed schedule, an issuer with $20bn outstanding would need $400m of operational risk capital before any revenue-based charge, and one with $60bn would need $950m. The tapering is a deliberate choice, since staff argue that operational risk does not grow in a straight line with size. It also means scale is rewarded. A small bank subsidiary pays the full 2 percent on every coin, while the largest issuer pays half that rate at the margin. Network effects already favour the biggest coins; the capital curve adds a regulatory tailwind.
Failure carries automatic consequences. An issuer below its minimum at a quarter end must file a plan. If it is still short at the end of the following quarter, it must liquidate its reserves and redeem all outstanding coins. Few banking rules are this unforgiving, and the design signals that the Fed sees a stablecoin issuer as a narrow utility, not a lender that can be nursed back to health.
A narrow business by design
The proposal confines supervised issuers to core activities such as issuing, redeeming and holding stablecoins in custody, plus what directly supports them. They would generally be expected not to carry material liabilities beyond the coins themselves or significant assets beyond reserves. The statutory ban on paying interest or yield solely for holding a stablecoin is implemented, and certain arrangements involving third parties would be presumed to be prohibited yield, following the approach the OCC has already proposed. That presumption deserves close reading by distribution partners that have relied on rewards programmes to attract balances.
For parent banks the treatment is equally strict. Under the GENIUS Act the Fed cannot make a parent hold more capital for its issuing subsidiary than the subsidiary itself must hold. The Board meets that requirement by having parents deconsolidate the subsidiary and deduct its minimum capital requirement from common equity tier 1. The bank cannot count the same capital twice. That makes a stablecoin subsidiary a direct claim on the parent's scarcest resource, and boards will weigh it against lending.
The Fed's reach also extends to state-chartered issuers. An uninsured state-qualified issuer with $10bn or more of coins outstanding would transition to Board supervision unless it wins a waiver, and would face an initial examination within six months of notifying the Fed. In unusual and exigent circumstances the Board could act against a state issuer after giving the state regulator 48 hours' written notice. Supervised issuers would file confidential weekly reports on issuance, redemptions, trading volume and reserves.
Dissent inside the consensus
Barr voted in favour but used his statement to mark the fault lines. He argued that stablecoins "will only be stable if they can be reliably and promptly redeemed at par in a range of conditions," and asked for comment on whether the rule adequately captures interest rate and foreign currency risk. He wants universal redemption rights clearly defined in the final rule. He also objected to a provision that would bar supervisory or enforcement action over an anti-money laundering deficiency unless it is "significant or systemic," a standard he said could have unknown effects on the Board's ability to confirm that programmes actually comply. According to PYMNTS, he added that "further work will undoubtedly be required if stablecoins are to be reliable payment instruments."
Time is a factor. The act takes effect on January 18, 2027, or 120 days after the primary regulators issue final rules, whichever comes first. Comptroller Jonathan Gould said in August that the OCC would have its final rule by November, PYMNTS reported. A 60-day comment window leaves the Fed little slack if it wants its own rules in place by the effective date.
Our view
The Fed has written a rulebook for a payments utility, not a bank. Reserves in short Treasuries, two-day redemption, a narrow activity list and a liquidation trigger after two quarters of capital shortfall all point the same way: a stablecoin issuer should be boring, and it should be paid for its boredom through float and scale rather than through risk. That is a defensible choice for holders. It is less comfortable for smaller banks and for fintech companies hoping to partner with them, because the graduated capital charge rewards the largest issuers and the CET1 deduction makes every subsidiary expensive for its parent.
Founders building on stablecoin rails should assume that distribution, not issuance, is where independent companies can earn a margin, and should read the third-party yield presumption carefully before designing rewards. Investors should watch three things during the comment period: whether the operational risk percentages move, whether diversification acquires hard limits, and whether the "significant or systemic" standard survives. Those details will decide whether bank stablecoins become a competitive market or a club.
Sources
- Federal Reserve: Federal Reserve Board requests comment on two proposals implementing the GENIUS Act (press release, September 24, 2026)
- Federal Reserve: Staff memo on notice of proposed rulemaking to implement the GENIUS Act for permitted payment stablecoin issuers
- Federal Reserve: Staff memo on applications procedures for insured state member banks seeking approval for a subsidiary to issue payment stablecoins
- Federal Reserve: Statement by Governor Michael S. Barr
- The Block: Fed proposes reserve limits, capital standards for stablecoin issuers under GENIUS Act
- PYMNTS: Fed proposes stablecoin reserve and capital rules under GENIUS Act
Filed under Fintech. Written by InvestTimes Editorial under our editorial standards. Commentary and analysis for information only, not investment advice.