The ECB raises rates again, and Europe's growth companies lose their cheapest year
Frankfurt lifted its deposit rate to 2.50% and refused to rule out more. Bond yields jumped to multi-year highs, and the bill will reach late-stage startups first.
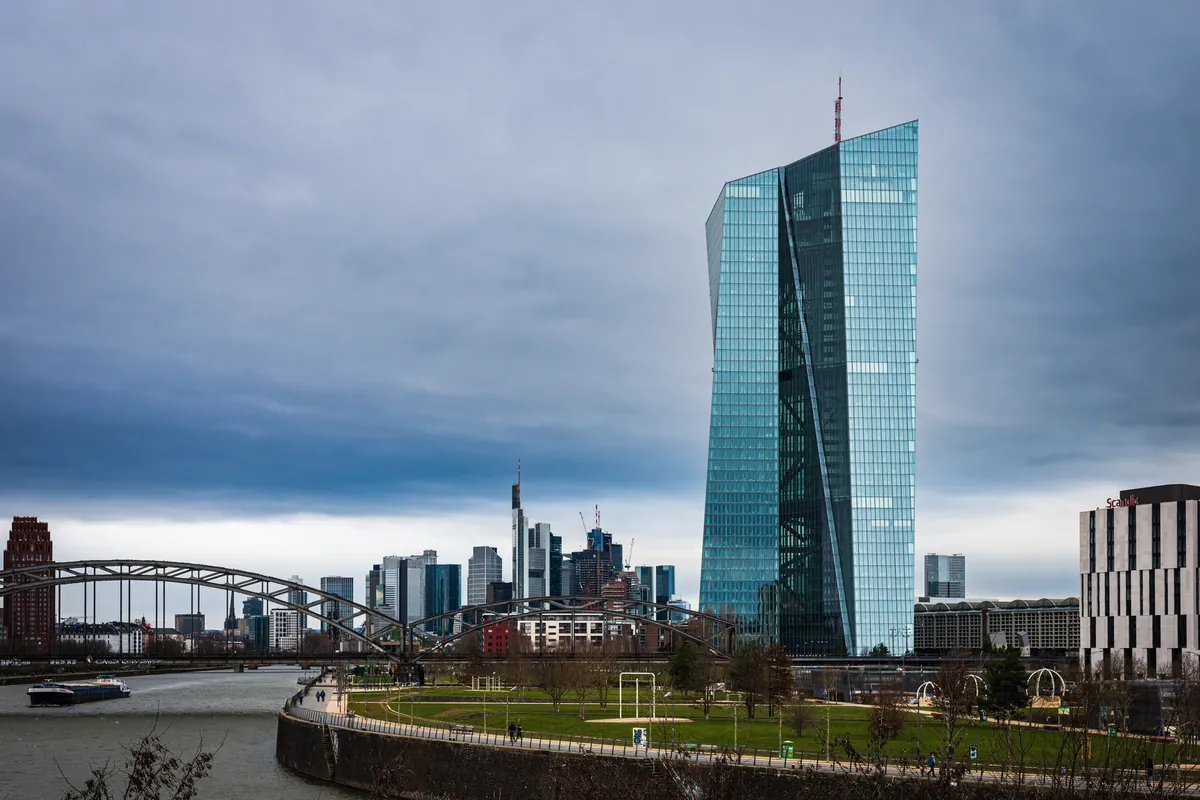
The European Central Bank raised its three key interest rates by 25 basis points on Thursday, September 10, lifting the deposit facility rate to 2.50%, the main refinancing rate to 2.65% and the marginal lending rate to 2.90%, with effect from September 16. It was the second increase since June, when the bank moved for the first time in three years, and it came with a message that matters more than the quarter point itself: the Governing Council said inflation is set to remain well above target for an extended period and declined to commit to any particular path for rates.
Markets heard a tightening cycle rather than a single correction. Money markets moved to price roughly 85 basis points of further increases by the end of 2027, up from just under 70 before the announcement, and a further hike by December became fully priced, according to Reuters. Germany's 10-year yield rose to its highest level since 2011. For European founders and the investors who back them, the decision ends any hope that the energy shock would be looked through, and it resets the cost of the money they have been raising at an unusual pace this year.
What Frankfurt decided, and why
The trigger is energy. Euro area inflation rose to 3.3% in August from 2.9% in July, with energy prices up 14.3% on the year after 10.3% the month before. The ECB attributed much of that jump to refining margins on liquid fuels and higher commodity prices, tied to the conflict in the Middle East and to the war in Ukraine. Fighting around the Strait of Hormuz has constrained crude supply, and Brent crossed $100 a barrel again on Wednesday, Euronews reported.
The underlying picture is less alarming. Inflation excluding energy and food eased to 2.4% from 2.5%, and services inflation fell to 3.0% from 3.3%. Wages, the ECB said, show no material response to the shock so far: compensation per employee grew 3.3% in the second quarter, down from 3.5%, and unit labour costs slowed to 2.6%.
Why hike, then? The staff projections give the answer. Headline inflation is seen averaging 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028, with the later two years revised up from June. Core inflation is expected to rise to 2.6% next year. The economy, meanwhile, has proved sturdier than expected, with growth projections lifted to 0.9% for 2026 and 1.4% for 2027, and unemployment unchanged at 6.4% in July. A central bank that sees resilient activity and upward revisions to inflation two years out has little room to wait, even when the source of the price pressure is a supply shock that interest rates cannot fix.
A bond market already on edge
The decision landed in a fragile market. On the day of the meeting, Reuters reported that long-dated borrowing costs hit multi-year highs across the region. France's 30-year yield reached levels last seen in 2003, and the gap between French and German 10-year yields widened to more than 90 basis points, the widest since 2012. Oil rose more than 4% to above $105 a barrel and European gas prices touched their highest since 2022. The STOXX 600 fell 0.6% and the euro slipped 0.1%.
The muted move in the currency is telling. A hike that is fully anticipated does little for the exchange rate when the Federal Reserve is expected to consider its own increase next week and the Bank of Japan is weighing one too. What did move was the long end of the curve, where investors are demanding more compensation for persistent inflation and for heavy government borrowing. Analysts cited France's coming election and its budget deficit as additional pressures.
The ECB is alert to this. Its risk assessment warns that spillovers in global bond markets could tighten credit conditions and dampen demand, and the press release reminded investors that the Transmission Protection Instrument is available against disorderly market dynamics. That language is a reminder, not a promise. It applies to unwarranted moves, and the bank gave no sign that it considers the current repricing unwarranted.
How the hike reaches private companies
The transmission to the real economy is already visible in the bank's own figures. Bank lending rates for firms rose to 3.8% in June and July from 3.6% in May, after the first increase. The cost of market-based corporate debt stood at 4.0% in July, well above its level before the conflict began. Lending to firms is still growing, at 4.4% a year in July, but that series usually reacts with a long delay.
Venture-backed companies do not borrow much from banks, yet they feel rate moves through three other channels. The first is venture debt and revenue-based financing, which is priced off benchmark rates and which many European growth companies use to extend runway between equity rounds. A deposit rate of 2.50% with more expected makes that bridge more expensive.
The second channel is valuation. Late-stage private rounds are benchmarked, explicitly or not, against listed peers whose multiples are sensitive to long-term yields. When the German 10-year sits at its highest since 2011, the discount rate applied to cash flows years away rises with it, and companies whose profits lie furthest in the future are hit hardest.
The third is the exit route. Listings and strategic acquisitions are what return capital to venture funds, and both become harder when equity markets wobble and acquirers face higher financing costs.
A strong year, built on large rounds
The timing is awkward because European venture had been recovering. Crunchbase data show Europe-based startups raised about $24 billion in the second quarter, the strongest quarter in four years, and $42 billion in the first half, up 50% on a year earlier. Late-stage funding reached $12.1 billion in the quarter, up 90%, and companies raising $100 million or more took 65% of the total. Four rounds of $1 billion or more made up a quarter of the quarter's investment, and AI companies absorbed more than $10 billion.
That concentration is the vulnerability. A recovery driven by a small number of very large late-stage rounds depends on investors who compare private valuations with public ones and who have alternatives. When safe euro assets yield more, the hurdle for illiquid growth equity rises. Seed and early-stage rounds, priced more on the founder and the idea, tend to be less exposed in the short run.
Our view
The ECB did what its projections required, and it was right not to pretend the energy shock would fade on its own. But founders and investors should take the bank at its word: no pre-commitment means rates can keep rising, and markets now expect them to.
The practical consequences are clear. Late-stage companies that planned to raise in the coming two quarters should assume tighter pricing and longer processes, and should treat venture debt as costlier than it was in the spring. Investors marking portfolios against listed comparables should expect pressure on those marks as long-term yields climb. The first-half rebound in European venture was real, but it rested on a handful of very large rounds that are the most rate-sensitive part of the market.
What to watch: the October inflation data and the next ECB meeting, the French-German spread as France's election approaches, and whether oil holds above $100. If energy eases, the cycle may stop short. If it does not, the cheapest year for European growth capital is already behind us.
Sources
- European Central Bank: Monetary policy decisions, 10 September 2026
- European Central Bank: Combined monetary policy decisions and statement, 10 September 2026
- Banco de España: ECB raises rates by 25 basis points in September
- Euronews: ECB hikes rates to 2.5% as energy shock pushes eurozone inflation higher
- Reuters via Investing.com: Bond yields hit multi-year highs as traders brace for new ECB rate-hike cycle
- Crunchbase News: Europe's Q2 2026 venture funding, AI and M&A up
Filed under Markets. Written by Invest Times Editorial under our editorial standards. Commentary and analysis for information only, not investment advice.